Bitcoin turns 18: Has the original rebel grown up?
Eighteen years ago today, pseudonymous cypherpunk Satoshi Nakamoto posted the Bitcoin whitepaper, Bitcoin: A Peer-to-Peer Electronic Cash System, to a cryptography mailing list.
Created to bypass opaque institutions and remove the need for trust in financial transactions, Bitcoin (BTC) has been taking on the traditional financial system since its genesis block was mined on Jan. 3, 2009.
Inscribed in that very first block was a message from Satoshi, quoting a headline from The Times: “Chancellor on brink of second bailout for banks.” It captured the financial crisis backdrop against which Bitcoin was born.
From its early years to adulthood, Bitcoin has had a tumultuous journey, fraught with controversy, intrigue and downright skulduggery.
As challenging as the journey has been, Bitcoin’s future remains on fragile ground, with the fallout from the $6.3 billion Binance hack, the threat of quantum computing, the acceleration of AI-related cyber threats, and questions over its long-term security still looming.
As Bitcoin celebrates its 18th birthday, it’s now old enough to vote in the US midterm elections, but is it ready for adulthood?
Bitcoin’s early years
Undoubtedly, one of Bitcoin’s most memorable moments was on May 22, 2010 when developer Laszlo Hanyecz sent 10,000 BTC to pay for two pizzas in one of the earliest documented Bitcoin transactions.
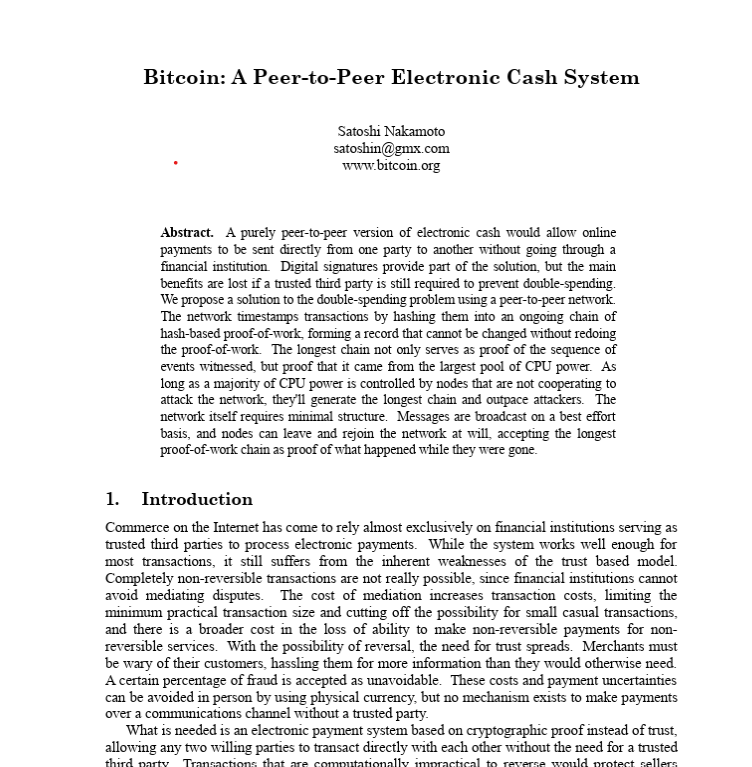
The Bitcoin Whitepaper. Source: Bitcoin.org
The day would become known as Bitcoin Pizza Day and go down in crypto folklore as the most expensive pizza purchase on record. The coins were worth around $41 at the time, taking the concept of opportunity cost to a whole new high — those pizzas would have cost $780 million at today’s prices.
Related: 10 of the greatest unsolved crypto mysteries
Bitcoin traded for pennies in its earliest days, but Satoshi understood how that would change one day, writing in 2009, “It might make sense just to get some in case it catches on.”
By late 2013, Bitcoin had broken through the $1,000 milestone for the first time, amid growing public interest with the emergence of the Silk Road darknet marketplace.
Yet nowhere do the laws of physics apply more pertinently than crypto; inevitably, what goes up must come down. In February 2014, Bitcoin’s epic run came to an abrupt end when Mt. Gox, the world’s largest Bitcoin exchange at the time, suddenly stopped trading and went offline.
The exchange had lost around 850,000 BTC, including customers’ funds, in a collapse that sent shockwaves through the industry, making Mt. Gox an early poster child for the concept “not your keys, not your coins.”
Craig Wright, Jamie Dimon and China’s first ban
The next dramatic bull run would culminate in Bitcoin’s price climbing from below $1,000 at the beginning of 2017 to almost $20,000 by December.
The rally coincided with a boom in initial coin offerings (ICOs) and a rush of projects promising to use blockchain technology for everything from banking to supply chains, and even Long Island iced tea.
Suddenly, every man, woman and dog wanted a blockchain, even if they had no idea how Bitcoin worked or where it came from.
Everyone, that is, except JPMorgan Chase CEO Jamie Dimon, who called Bitcoin “a fraud” in September 2017 and said he would fire any employee trading it.
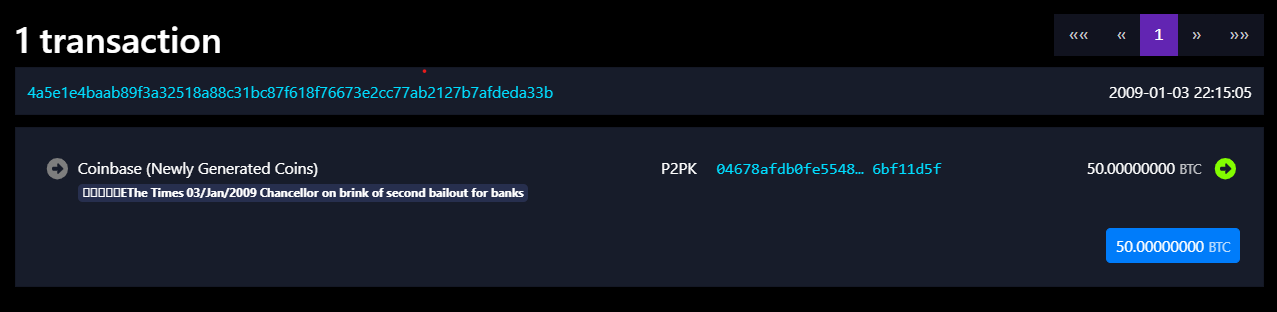
Bitcoin genesis block. Source: Mempool.space
At the time, Bitcoin was embroiled in a bitter debate over how the network should scale. The so-called “block size war” peaked in August 2017, culminating in the hard fork that created Bitcoin Cash and highlighting the complications of trying to change a decentralized system.
Related: Private, fast USDT is coming to Bitcoin. Can it compete with Ethereum and Tron?
Meanwhile, China moved against the industry, banning ICOs in September 2017, taking action against cryptocurrency exchanges and fanning the market uncertainty ahead of the eventual downturn in 2018.
Speculation over the identity of Bitcoin’s creator had also become a sideshow, fueled by Australian computer scientist Craig Wright’s repeated claims to be Satoshi Nakamoto. The UK High Court rejected his claim in 2024.
China’s second ban and the collapse of FTX
Bitcoin’s next major bull run came during the COVID-19 pandemic, as governments and central banks unleashed a tsunami of money printing in a bid to cushion economies from lockdowns.
Interest rates fell, liquidity flooded financial markets and Bitcoin, which had plunged during the March 2020 market panic, began a remarkable recovery, reaching almost $69,000 by November 2021.
As if China’s intervention wasn’t enough the first time around, Beijing stepped in again to rain on the parade, announcing a sweeping ban on cryptocurrency transactions and mining in September 2021, and Bitcoin’s price took a hit.
In November 2022, another major cryptocurrency exchange, FTX, collapsed, intensifying the crypto winter and leaving customers facing enormous losses.
The episode led to a loss of trust from the TradFi sector and a spate of regulatory hostility toward crypto, in what the industry would dub “Operation Chokepoint 2.0.” Bitcoin’s downward spiral was once again painful and steep.
The first Bitcoin ETF and $100,000
Just when sentiment in the industry was circling the drain, a silver lining appeared in January 2024 from one of the unlikeliest sources. The US Securities and Exchange Commission, which had repeatedly rejected spot Bitcoin product applications, approved the first US spot Bitcoin exchange-traded products.
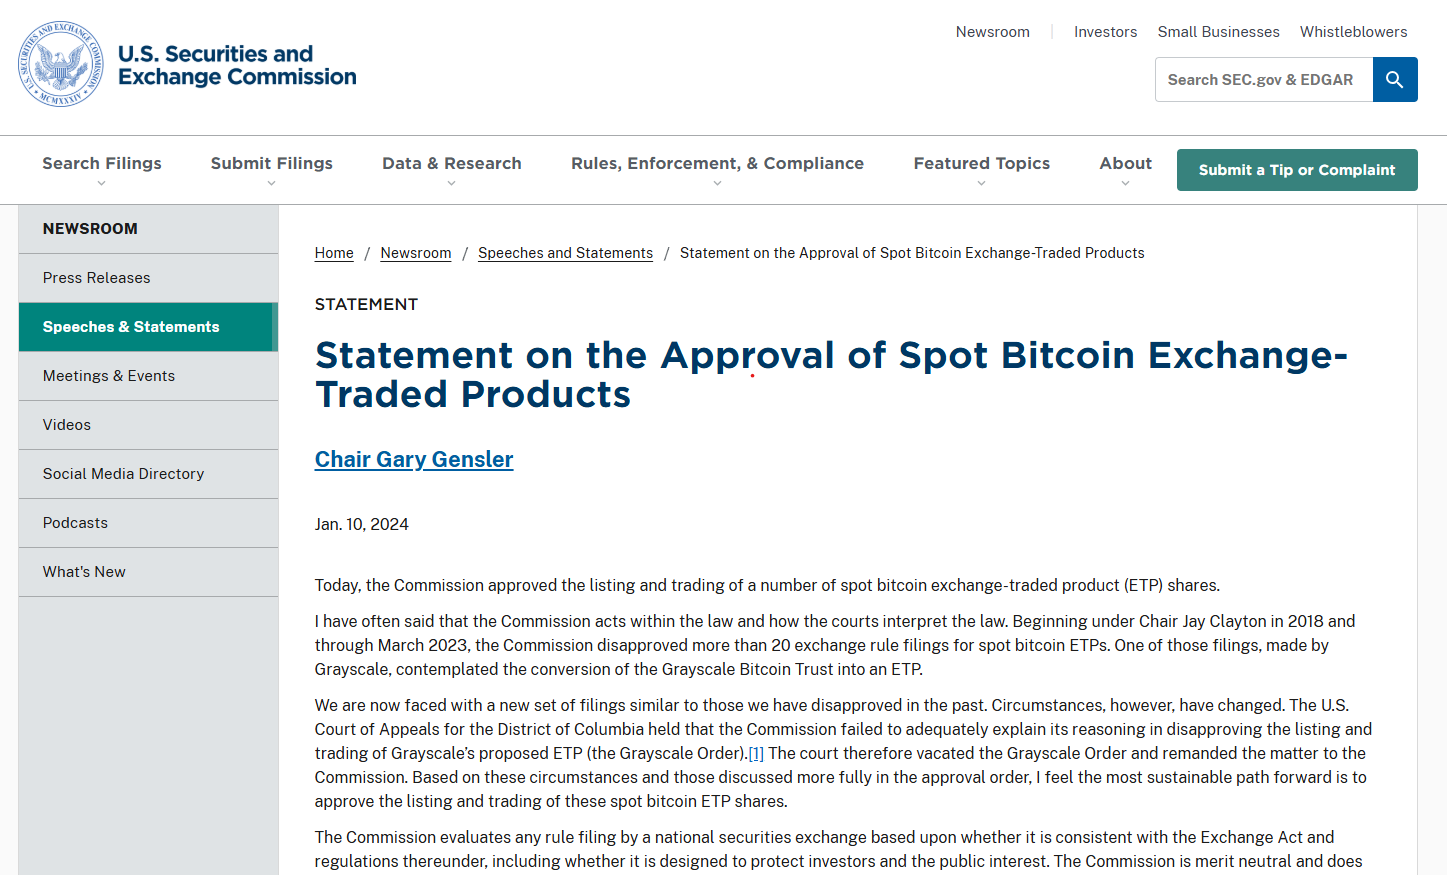
The SEC approved a US spot Bitcoin ETF. Source: SEC.gov
The nod from the SEC finally gave investors a regulated route to gain exposure to BTC without having to manage wallets or private keys themselves. At the end of that year, Bitcoin’s price broke through $100,000 for the first time.
Related: Bitcoin ETF inflows climb to $176M as BTC rebounds above $80K
Since then, traditional finance has continued to move closer to crypto, with banks moving into custody and trading services and heavyweights like BlackRock CEO Larry Fink talking about putting everything from stocks to bonds on the blockchain.
Even Dimon shifted his stance from outright dismissal to allowing clients to buy the asset. The original cryptocurrency went on to hit a new all-time high of more than $126,000 in October 2025.
Bitcoin’s all grown up, but what about the future?
Bitcoin is firmly in the embrace of TradFi once again, with some sizable regulatory tailwinds from Washington and abroad.
The Guiding and Establishing National Innovation in US Stablecoins (GENIUS) Act has established a federal framework for stablecoins, the SEC has offered greater clarity on how securities laws apply to crypto assets, and Europe’s Markets in Crypto-Assets Regulation (MiCA) has given the local industry a more harmonized regulatory framework.
Yet the institutionalization of the space has led many Bitcoiners to question whether institutions holding so much BTC are concentrating ownership and centralizing supply — and indeed whether the cypherpunk movement has been captured by the very institutions it sought to rebel against.
There are bigger questions looming over Bitcoin’s long-term security, too, including the threat of quantum computing, which many fear could break the cryptography that secures Bitcoin.
A proposed upgrade known as BIP-360 outlines a new type of Bitcoin output to reduce certain quantum vulnerabilities, but as the community learned from the block size war, the challenge will be agreeing on any new implementation before the threat arrives.
And quantum computing is not the only security question Bitcoin needs to resolve. This week’s $6.3 billion Binance hack, the largest crypto exchange hack on record, has renewed fears about the security of centralized exchanges, the stability of crypto infrastructure and the potential for further market turmoil.
There’s also the question of who pays to keep the network secure as the block subsidy trends to zero, and whether transaction fees alone will be enough to compensate the miners securing the network.
Transaction fees accounted for just 0.67% of total miner revenue in the 90 days to Oct. 4 and have remained below 5% of miner revenue for most of Bitcoin’s history. That leaves a huge gap for fees to fill as block rewards diminish with each halving.
Happy 18th birthday, Bitcoin
Bitcoin has endured more than your average teen as it comes of age, surviving exchange collapses, regulatory crackdowns, civil wars and repeated market crashes.
It has also become something Satoshi may not have foreseen: an asset held by Wall Street and traded through mainstream financial products.
Magazine: Will gold’s ‘infinite mint bug’ make Bitcoin more valuable?