


Winners and losers of the SEC’s new tokenized stocks rules
“Tokenization is coming to America,” said Robinhood chief executive Vlad Tenev after the SEC announced its Innovation Exemption last week — and it seems the markets looked kindly on the development.
BTC and ETH soared over 10%, and Uniswap’s UNI token — a protocol that looks as it if could become prime real estate for tokenized stock trading — gained more than 30% in the days that followed.
While the Securities and Exchange Commission has indeed greenlit tokenized stocks in America, most of the existing stock tokens fall outside of the new rules.
The commission’s new five-year Innovation Exemption creates a path for certain venues to trade tokenized National Market System (NMS) stocks onchain without registering as a securities exchange, and for third parties to tokenize stocks — but only under a specific set of conditions.
Tokens must give holders the same “rights and privileges” as the underlying shares and trading venues need to permission users and pools.
Related: Kraken brings DeFi yield to tokenized stocks and ETFs
Not all tokenized stocks are created equal. A token can look like a share and track the price of a share without providing the shareholder rights of a share. Under the new rules that’s classified as a synthetic stock and it’s not compliant.
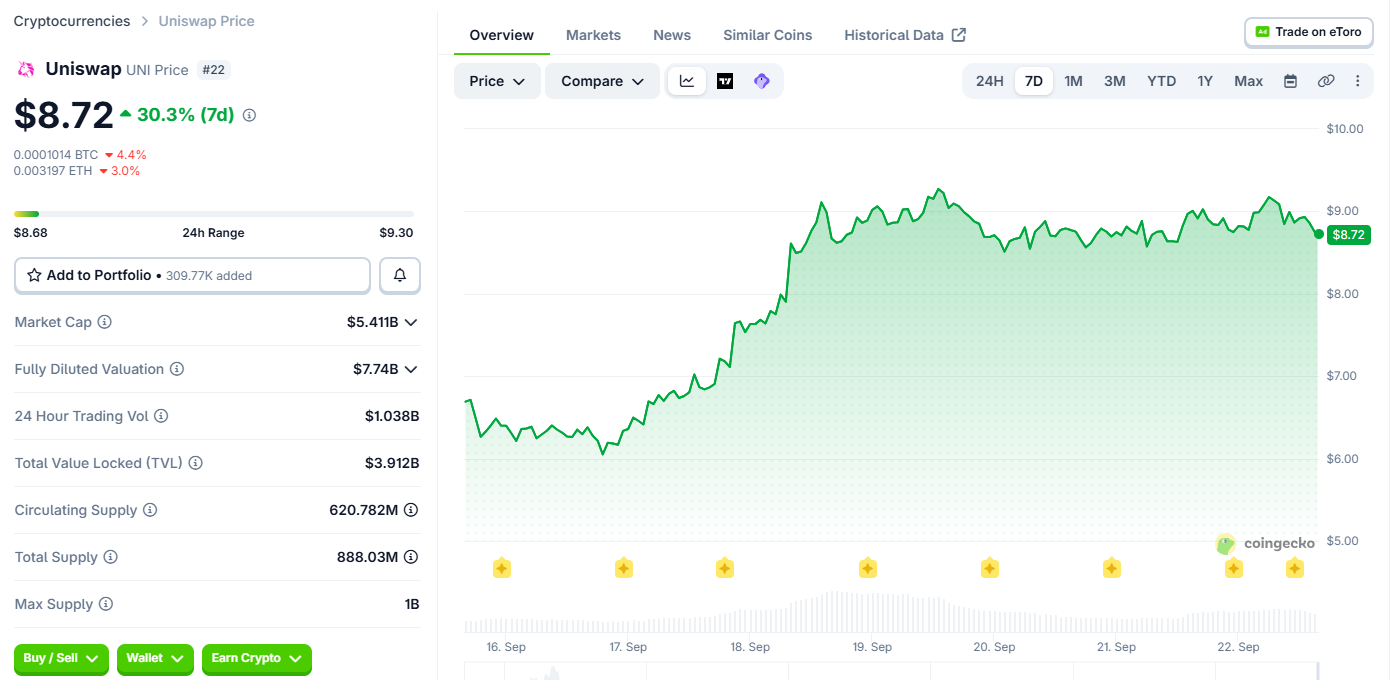
UNI gained over 30% after the SEC announcement. Source: Coingecko
That means some of the industry’s biggest players may already have a head start, while others will have to play catch-up. As Ondo Finance’s head of global regulatory affairs, Peter Curley, tells Magazine:
“Not everything we do will fit, and that’s fine. What matters is that the SEC acted instead of waiting on Congress to finish the job.”
The SEC’s tokenization lane is narrow
The SEC’s Sept. 17 order gives certain venues temporary relief from having to register as exchanges when they trade tokenized NMS stocks through permissioned AMM liquidity pools.
In other words, the agency has opened a lane for onchain stock trading, but it’s a fairly specific one, and the token itself becomes just as important as the venue.
To qualify, a tokenized stock must give holders the same dividends and voting rights as the underlying security.
While a third party can tokenize a stock without being affiliated with the issuer, the issuer gets a chance to nix the token before it can be traded.
That rules out synthetic exposure which is bad news for Robinhood’s Stock Tokens and Kraken’s xStocks in their current forms.
Commissioner Hester Peirce stressed that the exemption covers one particular model rather than every possible way of trading tokenized securities, although she said the SEC is open to other models outside the TSV structure.
The products closest to the SEC’s model
Coinbase’s stock tokens are in the ballpark.
On Sept. 14, chief executive Brian Armstrong said the company had “set the standard” with its tokenized stocks, as they are not synthetic or debt instruments, but are “real fully-backed securities, redeemable for the underlying shares, with dividends integrated,” and voting rights “coming soon.”
Related: Robinhood chain to generate $160M in annual fees by 2028: Bernstein
However, Coinbase’s current tokenized stock offering is for non-US customers, and its exchange infrastructure is built around a central limit order book. The SEC’s exemption is built around TSVs providing permissioned AMM liquidity pools. Coinbase operates the Base network however, so it has options in that regard.
Ondo launched tokenized US securities in June, with the underlying shares held in traditional custody and the token representing the investor’s entitlement onchain.
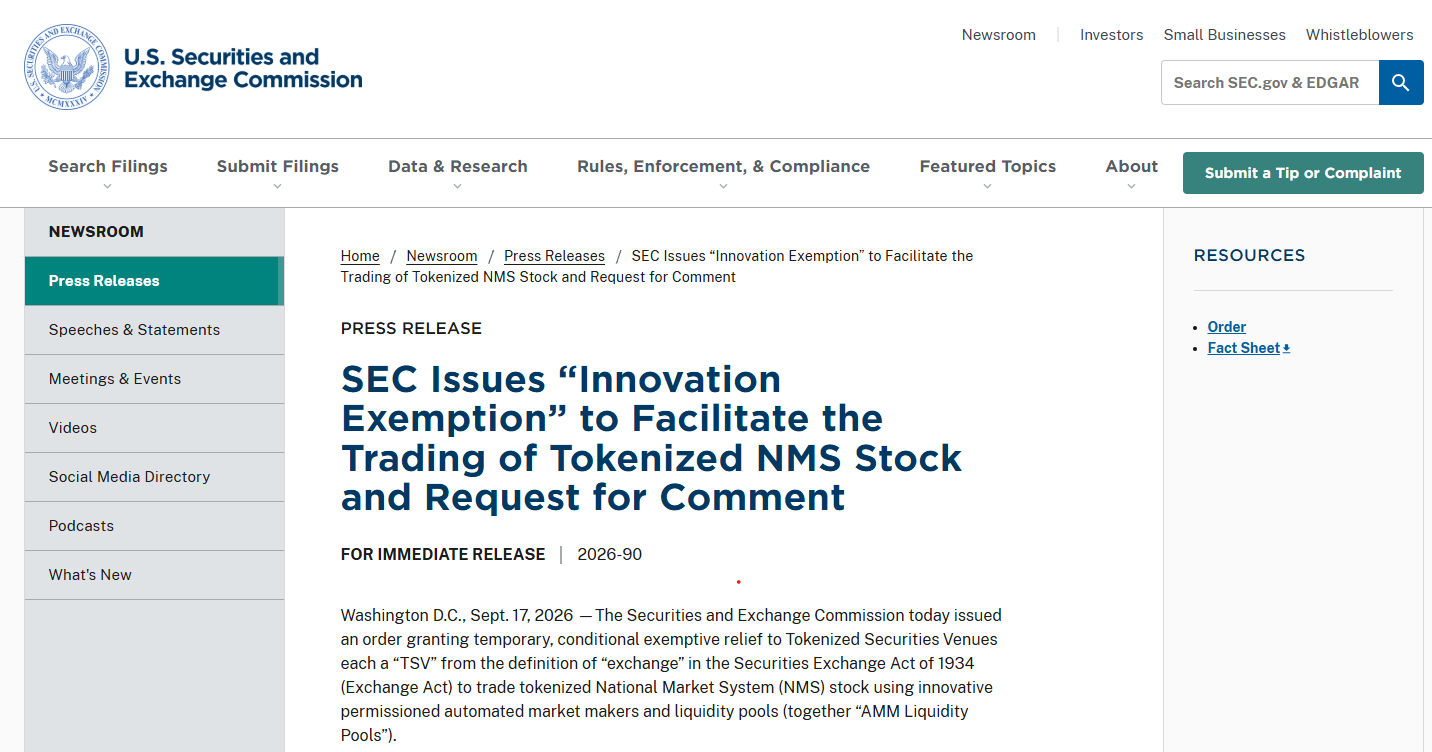
SEC issues Innovation Exemption. Source: SEC
It also acquired Oasis Pro, which includes an SEC-registered broker-dealer, ATS and transfer agent, with infrastructure across the traditional and onchain sides of the market.
Curley says the SEC’s exemption favors “exactly the model we’ve already proven out: custodial, entitlement-based, with real shareholder rights and corporate actions passing through to the holder.” However, he adds, “we’re not assuming anything clears automatically.”
Both Coinbase and Ondo have pieces of the infrastructure the SEC seems to want. Neither can assume its existing setup qualifies without some finessing, but they may have less to rebuild.
Uniswap’s permissioned pools could open the door
The SEC exemption is specifically designed around permissioned AMM liquidity pools, which looks like being good news for Uniswap.
The protocol introduced Permissioned Pools for v4 in July, allowing regulated assets to trade through AMMs with compliance enforced directly onchain.
While that doesn’t make Uniswap itself a TSV, its v4 infrastructure could be used by operators building one, as Permissioned Pools let issuers control who can trade or provide liquidity, which is consistent with the SEC’s requirements.
Permissioned access requires Know Your Customer (KYC) verification, record keeping, public notices and transaction transparency.
If that infrastructure can be connected to the shareholder rights and regulatory infrastructure required for US securities trading, Uniswap potentially has a framework that could be adapted to the SEC’s model.
Robinhood has the users, but not the right product
Robinhood already has around 200 stock tokens trading on Robinhood Chain, which Tenev has described as one-to-one backed and fully DeFi composable.
But the head of research at Four Pillars, Jaewon Kim, pointed out that the SEC’s order excludes synthetic exposure, which rules out products like Stock Tokens and Kraken’s xStocks.
Robinhood’s Stock Tokens are tokenized debt securities issued by Robinhood Assets (Jersey) Limited. That means they provide economic exposure to the underlying stocks but don’t give holders legal or beneficial rights. They’re also not registered under US securities laws and not available to US persons.
Chairman Paul Atkins says the period will allow the market to “develop.” Source: SEC
But while Robinhood’s existing product doesn’t fit the SEC’s rules, its distribution and blockchain infrastructure could give it a big advantage if it can adapt its model to the new requirements.
Kraken’s xStocks are fully backed by underlying equities but they also don’t give holders the same rights as conventional shares. And being backed by shares is not enough to qualify for this exemption.
Bryan Choe, head of research and operations at RWA.xyz, a market intelligence platform for tokenized real-world assets (RWAs), says most existing tokenized equity products are currently third-party sponsored, but he expects that to change in the next 12 months.
He tells Magazine, “We expect most of the products to shift to issuer-sponsored models.” He says the exemption “aligns the token issuers with the stock issuers,” and could bring more balance between different issuance models.
Five years to prove tokenized stocks are actually better
The SEC describes the exemption as temporary, and chairman Paul Atkins says the five-year-long period will allow the market to “develop” while the commission “evaluates future rulemaking.”
Beyond which company gets the first compliant venue, the real test is whether tokenized stocks will take off in the first place.
As Curley says, investors need to end up with something “faster, cheaper, or more useful than a conventional brokerage position.” Questions have already been raised over whether the fragmented liquidity for stock tokens will provide good prices or a decent user experience.
The exemption could enable 24/7 trading, fractional ownership, faster settlement, onchain composability and shareholder rights. But at the end of the day, those advantages only matter if investors actually care.
Related: Is there any chance left to save the CLARITY Act?
Cointelegraph publishes long-form journalism, analysis and narrative reporting produced by Cointelegraph’s in-house editorial team with subject-matter expertise. All articles are edited and reviewed by Cointelegraph editors in line with our editorial standards. Some articles contain affiliate links, from which Cointelegraph may earn a commission. These relationships do not influence which products we review or our editorial conclusions. Content published in here does not constitute financial, legal or investment advice. Readers should conduct their own research and consult qualified professionals where appropriate. Cointelegraph maintains full editorial independence.